


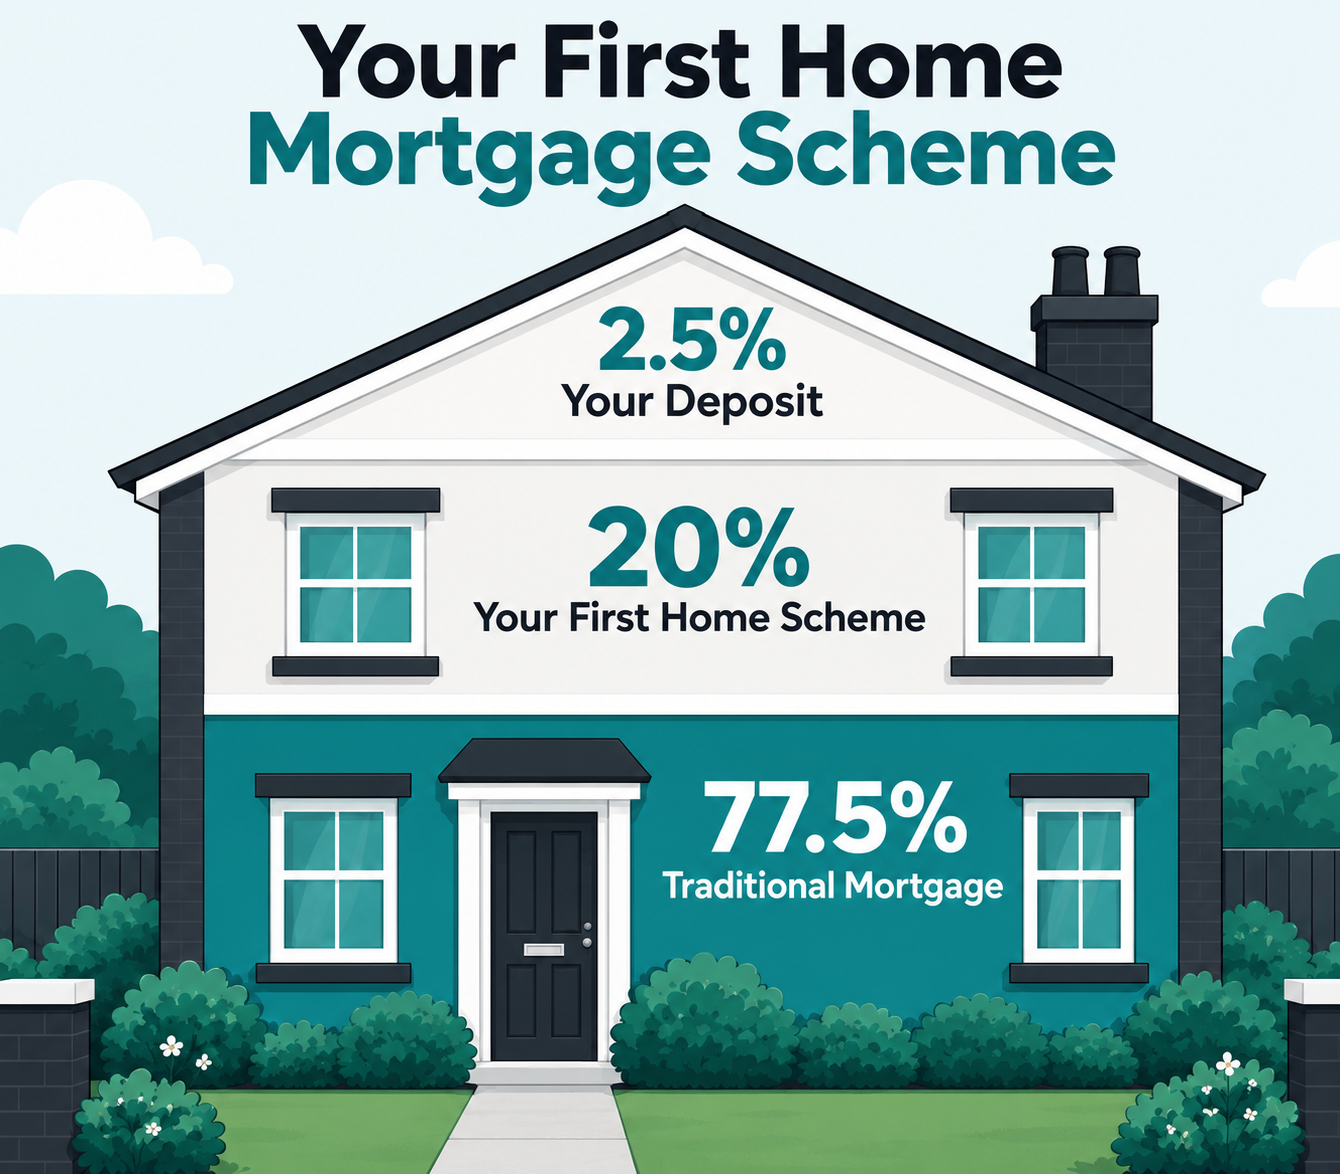
What is ‘Your First Home’?
On the 26th of September 2026. Andy Burnham confirmed a new scheme that’s designed to help first-time-buyers get on the housing ladder.
The fine details of the scheme are to be announced following the Autumn Budget on the 28th of October 2026.
The scheme will be the first of its kind since the Help-to-Buy equity loan scheme launched in 2013. The advisers at Advantage FS have loads of useful experience with the last Help-to-Buy scheme, here we answer what we know so far about ‘Your-First-Home’.
What we know so far:
- Available to First Time Buyers
- Available in England
- An Equity Loan of 20% of the property value will be provided by the government
- The Equity Loan will have an interest free period, during which time no interest will be charged or accrued
- Applicants will require a deposit of at least 2.5%
- There will be a household income cap, determined geographically
- Only available on new-build properties
- Only available with developers that are registered under the scheme.
What we don’t know: (Until the Autumn Budget)
- We don’t know if the scheme will be available to foreign nationals
- We don’t know the overall term limit to the equity loan (Help-to-Buy was 25 years)
- We don’t know the interest rate terms
- The definition of a ‘First time Buyer’
Who is it for?
Your-First-Home is designed to overcome the deposit barrier faced by so many would-be home owners. If you’re looking to purchase your first home and have a good income and credit history, the scheme is designed to allow you to buy sooner rather than later. It is expected to be popular as tackles the main challenge faced by renters, that being that it’s hard to pay rent and save for a house deposit at the same time.
Who is it not for?
If you have a deposit of 20% or more, the scheme is unlikely to be suitable for you. If you have a deposit of around 10% or 15%, it’s especially important that you seek independent mortgage advice before making a decision. The scheme is not there to help prospective buyers buy a more valuable home than they otherwise would be able to afford. Mortgage lenders will be required to calculate affordability differently for anyone using the scheme.
How will it work?
The Equity-Loan provided by the government is secured against the property in the form of a legal charge on HM Land registry. Importantly, the Government doesn’t normally own 20% of the legal title in the same way as a co-owner. The arrangement is secured by the legal charge, while the amount you ultimately owe is linked to the relevant percentage of the property’s value under the scheme.
The previous Help-to-Buy Scheme was interest free for 5 years, so far the assumptions are that Your-First-Home will be the same. Likewise, interest will become payable against the original amount borrowed based on some pre-determined rules. The old scheme was based on a set percentage plus an additional amount linked to the Consumer Price Index.